Your building is fine. Your business has stopped.
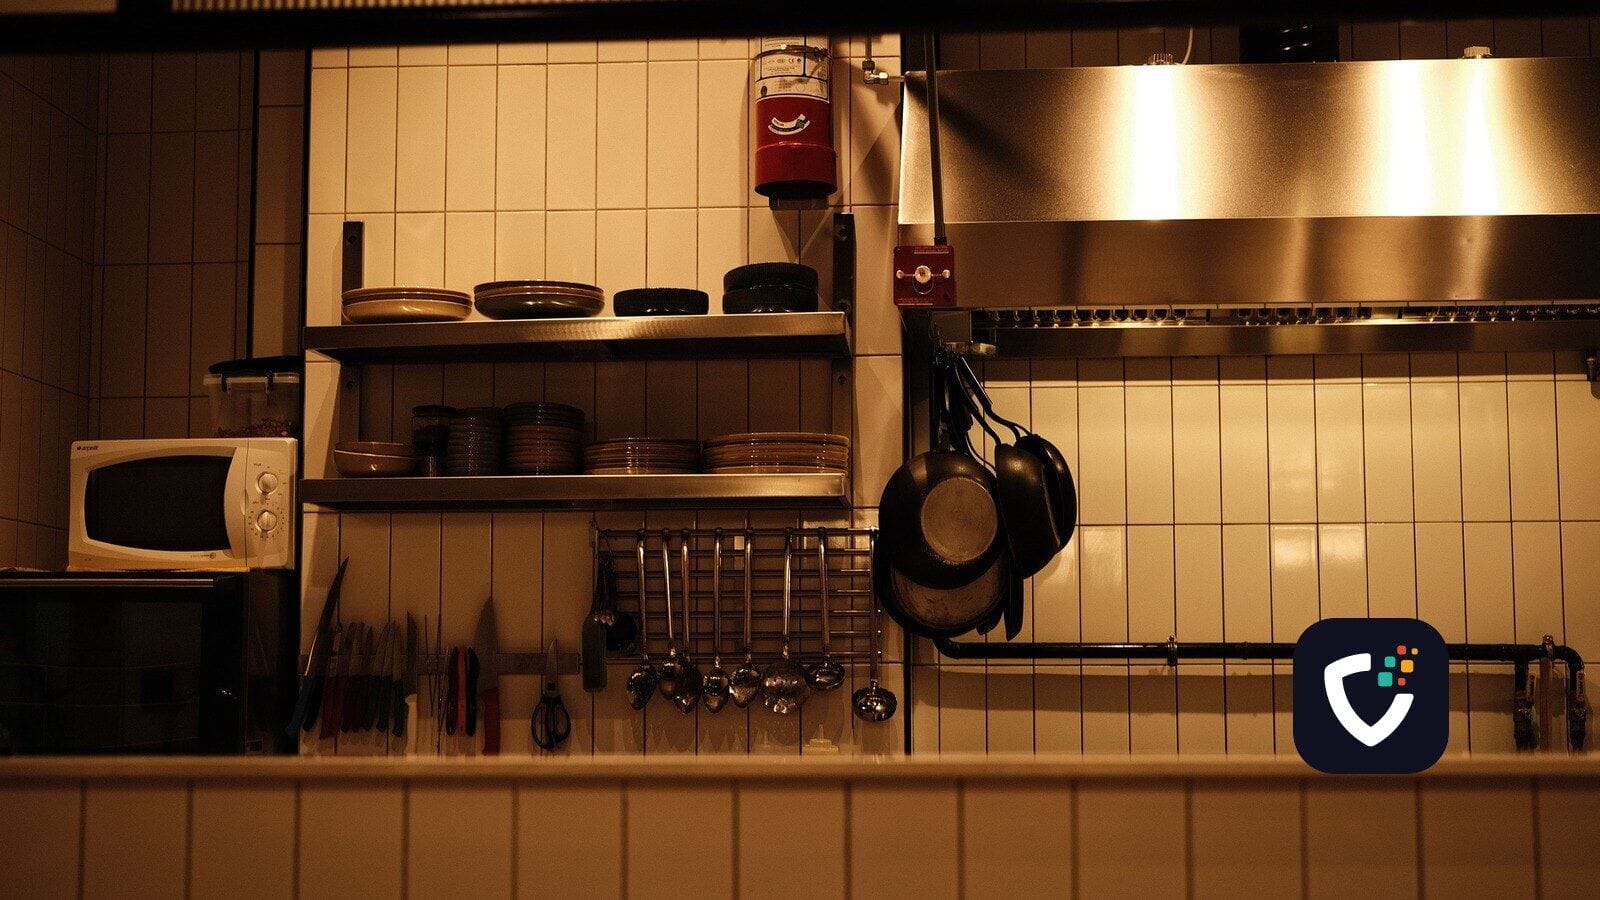
Imagine arriving at a small UK food business after a disruption elsewhere in the area. The roof is intact, the equipment is where it should be and the stockroom looks normal. But an essential external service is unavailable, and the business cannot carry out its usual work.
There is little to photograph. That does not mean there is little to lose.
This hypothetical scene exposes a blind spot in how a business can picture its own resilience. The premises are a place it occupies. The operation extends far beyond them.
For insurers, brokers and the businesses they work with, the useful conversation begins with that distinction. What has to keep functioning for this particular business to trade, and which of those dependencies sit outside its walls?
The boundary fence does not contain the business
A building provides a convenient way to organise a discussion. It has an address, an owner, a physical condition and a set of contents. An operation is less tidy.
A business may depend on an external utility, a specialist supplier, a route into the site or another organisation’s ability to complete a particular task. Which dependency matters most will vary. The important point is that the source of a stoppage need not be inside the premises.
The Government Office for Science’s June 2026 supply-chain Foresight report describes how vulnerabilities can sit several steps back in production networks or at shared transport routes and chokepoints. Its focus is goods supply chains and possible future conditions, not an insurance coverage assessment. Government Office for Science, global supply chains foresight report.
For an individual firm, the implication is a question rather than a forecast: which external failure would make its apparently healthy premises unable to deliver the product or service customers expect?
The answer may be surprisingly ordinary. It does not have to involve the largest supplier by spend or the most expensive asset on the balance sheet.
Operational importance is about what the business can do without something, not simply what that something costs.
Disruption and insurance cover are different questions
The phrase business interruption sounds broad. A policy has a more particular meaning.
The Association of British Insurers explains that business interruption cover responds to specified circumstances and perils. It also notes that some policies may include restricted-access or non-damage cover, which it describes as usually an addition to a standard policy that can cost more. So the cover most relevant to an undamaged building is often the part a business has to have chosen and paid for. The actual wording matters. ABI, business interruption insurance.
That makes it unsafe to infer a payout from the sentence “We could not trade.” Equally, an undamaged building does not by itself establish that no relevant cover could exist. The cause, the policy and any applicable extensions need to be examined together.
For the hypothetical food business, the operational question is what the missing service prevents it from doing. The insurance question is whether its particular contract responds to that event and loss, subject to its terms and limits.
Those questions should meet before a crisis. A practical discussion with a broker or insurer can begin with a concrete interruption scenario and work through what is and is not addressed by the existing arrangement.
The aim is an accurate understanding, not the reassuring appearance of a broadly named policy section.
An alternative is only useful if it can work in time
“We could use another supplier” is an appealing answer. It is also the beginning of a conversation rather than its conclusion.
Consider a hypothetical specialist input. An alternative supplier may exist, but the business may need to confirm compatibility, agree terms, arrange delivery or obtain the necessary customer approval before using it. That is different from having a ready replacement.
Two suppliers can also share a vulnerability further back in the chain. The Government Office for Science report highlights the importance of indirect connections and common dependencies when examining resilience. Government Office for Science, global supply chains foresight report.
None of this proves that holding more stock or adding another supplier is always the right answer. Those choices have costs and practical limits. Perishable goods, constrained storage and specialist requirements can make apparently simple solutions complicated.
The useful test is whether an alternative has been explored far enough to understand what it would require. Who would contact whom? What would need checking? Which parts of the operation could continue while the rest waited?
A business does not have to eliminate every dependency to understand its options more honestly.
Recovery has more than one milestone
The power returns. The road reopens. The supplier resumes production. Each can be an important milestone without marking a complete return to normal trading.
A hypothetical business might still need to check equipment, replenish inputs, reschedule work or reconnect with customers who have made other arrangements. The recovery sequence depends on the actual operation.
Allianz’s guidance to intermediaries on indemnity periods includes supply dependencies, asset replacement, inventory and revenue recovery among the considerations. It is an insurer’s professional perspective, not a universal formula for the right period for every business. Allianz UK, setting indemnity periods.
The value of that discussion lies in giving time a more realistic shape. “Back in the building” and “back to the expected level of trade” may refer to different stages.
When insurance arrangements are reviewed, the period and basis of cover need to be considered alongside the business’s own recovery assumptions. A generic number of months cannot substitute for understanding those assumptions.
The practical question is not only what can be restarted. It is what has to happen before the business is doing the work, serving the customers and earning the income its plan depends on.
Put the operating story beside the policy
A productive review can start with one ordinary scenario and the people who understand it.
The operations colleague explains what would stop. Purchasing describes alternatives and constraints. The person responsible for customers explains which commitments would be affected. The broker or insurer can help examine how the policy relates to the scenario.
Allianz’s public business-interruption explanation directs readers to their wording and schedule when assessing whether particular extra expenses could be covered. Allianz UK, cover for business interruption. That is a useful discipline for the broader conversation: move from the label to the actual arrangement.
There is room here for proportion. A small business does not need to produce a model of the entire world before identifying a few important dependencies. Nor should an honest review pretend that every gap has an affordable solution.
What it can do is separate an understood exposure from an unexamined assumption. A decision to accept a risk after considering the alternatives is different from discovering that nobody had realised it existed.
The discussion also deserves revisiting when the operation changes. A new product, a different supplier or a larger commitment to a customer can change the story even if the building looks exactly the same.
Look for the failure the photograph cannot show
Return to the food business with its intact roof and idle operation. The absence of visible damage does not tell us the cause of the problem, the path to recovery or whether a policy responds.
Those answers require a closer understanding of how the business works.
The most useful insurance conversation may therefore begin away from the building valuation and the list of contents. It may begin with the ordinary things arriving from elsewhere, the people and services behind them, and the time needed to find another way to operate.
A building can be in excellent condition while the business inside it is waiting for something it cannot provide for itself.
If everything within your boundary stayed intact tomorrow, what outside it could still stop you trading?
Make every report count.
Tell us what your team reports and we will show you how it works in Logincident.
Contact us